US Economic Outlook
The Federal Reserve revised its outlook during the second quarter because of its inflation forecast, not the current inflation reading. In June, Committee members raised their expectation for 2026 headline PCE inflation to 3.6% from 2.7% in March. They pointed to conditions under which price pressures could persist, specifically the continuing conflict in the Middle East, tariffs, and the demand generated by investment in artificial intelligence. What changed was the Committee’s view of how long elevated inflation would last.
Events since quarter end have supported that caution. Brent crude traded at $71 per barrel immediately before the conflict began in late February, peaked at $138 on April 7, and fell to approximately $70 by June 30 following a mid-June agreement for a tentative ceasefire between the United States and Iran. That arrangement has since broken down, and oil prices have risen again amid renewed conflict. Brent reached $105 on July 23 before settling at approximately $92 on July 31, while retail gasoline rose from $3.78 per gallon in early July to $4.10 by the end of July.
Inflation itself remains elevated and continues to be driven primarily by energy. Headline PCE inflation rose from 3.5% in March to 4.1% in May before easing to 3.7% in June. Core PCE, which excludes food and energy, moved from 3.2% in March to 3.4% in May and 3.3% in June. The narrow move in core relative to headline indicates that the acceleration has been concentrated in energy and is not broadly based. That qualifies, but does not reverse, our observation last quarter that price pressures were beginning to broaden. Core PCE remains above its March level and well above the Federal Reserve’s 2% target.
The labor market has been characterized by low hiring and low firing. June nonfarm payrolls increased by just 57,000, and April and May were revised down to 148,000 and 129,000, a combined downward revision of 74,000. The unemployment rate declined to 4.2% in June from 4.3% in March, but the improvement reflects a contraction in the labor force rather than hiring. Labor force participation fell 0.3 percentage points from 61.8% in May to 61.5% in June, which is the lowest level since March 2021. Layoffs, however, have not accelerated. The pattern remains consistent with the labor market we described last quarter, which had stopped expanding but had not broken.
The more immediate pressure on households is the erosion of real income, not the loss of employment. Average hourly earnings rose 3.5% year-over-year in June, and the Atlanta Fed Wage Growth Tracker eased to 3.6% in June from 3.9% in March. With headline PCE inflation at 3.7%, nominal wage growth is no longer keeping pace with prices. Research from the Federal Reserve indicates that higher-income households continue to realize real income gains while lower- and middle-income households do not, extending the K-shaped pattern we have described since 2024. Households have maintained spending by reducing savings, with the personal saving rate falling from 4.4% in January to 2.7% in June, its lowest level in several years.
Spending has held steady in nominal terms, though real volume growth has been roughly flat. The advance estimate of second quarter GDP showed real growth of 1.5% annualized, down from 2.1% in the first quarter.
The Commercial Real Estate Landscape
Commercial real estate remains in a phase of uneven recovery, and the headline figures do not tell the entire story. Second quarter transaction volume totaled $113.7 billion, an increase of 9% year-over-year, but that gain was neither steady nor broad. April volume fell 33% year-over-year to $24.7 billion, the first annual decline since mid-2025, before May rebounded to approximately $42 billion, up 15% from a year earlier. That increase did not come from property sales. Mergers and acquisitions accounted for $6.8 billion of the month’s volume, while single-asset volume declined 4%. Entity-level deals are lumpy, driven by corporate strategy, and establish little about the price at which an individual building trades. Single-asset sales are the better measure of whether the market is clearing.
Pricing has stabilized without recovering. Green Street’s all-property index was unchanged in June and up 4.1% year-over-year, though it remains roughly 14% below the 2022 peak, while the MSCI RCA index, which measures closed repeat sales instead of current opinions of value, rose only 0.9% year-over-year in the second quarter. A persistent bid-ask spread continues to constrain single-asset deal flow.
Sector performance diverged sharply. Senior housing produced an unlevered total return of 3.91% in the second quarter, the strongest of any sector in the NCREIF Property Index, which returned 1.29% overall. Occupancy across NIC’s 31 primary markets reached 89.9%, the twentieth consecutive quarterly increase, set against inventory growth of 0.4% and fewer than 16,000 units under construction, a level last seen in 2012. Multifamily fundamentals also improved, with second quarter net absorption of 187,000 units lifting occupancy to 95.5% and trailing-year deliveries falling to approximately 340,200 units. Apartment pricing, however, has not followed. Values remained 1.7% below year-ago levels on a repeat-sales basis, with effective rents 0.2% lower.
For commercial real estate, the prevailing expectation through this cycle has been that when the Federal Reserve resumes cutting, long rates will follow, providing relief on borrowing costs and allowing values to recover. The Federal Reserve held the federal funds target rate at 3.50–3.75% at its July meeting, but the Committee’s internal debate reflected the shift in its forecast. While the target rate has been unchanged so far this year, the direction of dissent has reversed. Members dissented in favor of cuts in January and March. At the April meeting, the Committee voted 8–4, with only one member favoring a cut and three supporting the hold but objecting to statement language implying that the next move would be a cut. At the July meeting, all three dissenting members favored a 25 basis point increase. The June projections placed the median year-end 2026 federal funds rate at 3.8%, up from 3.4% in March.
The yield curve steepened sharply in July, with roughly half the move in long yields coming in the three days after the July FOMC meeting. Measured from the end of the second quarter, three-month Treasuries fell 4 basis points to 3.83%, while the two-year rose 14 basis points to 4.28%. Over the same period, the 10-year rose 31 basis points to 4.75%, and the 30-year rose 36 basis points to 5.27%, its highest level since July 2007 and roughly 165 basis points above the effective federal funds rate. The spread between the two-year and the 30-year widened from 77 basis points at the end of June to 99 basis points on July 31.
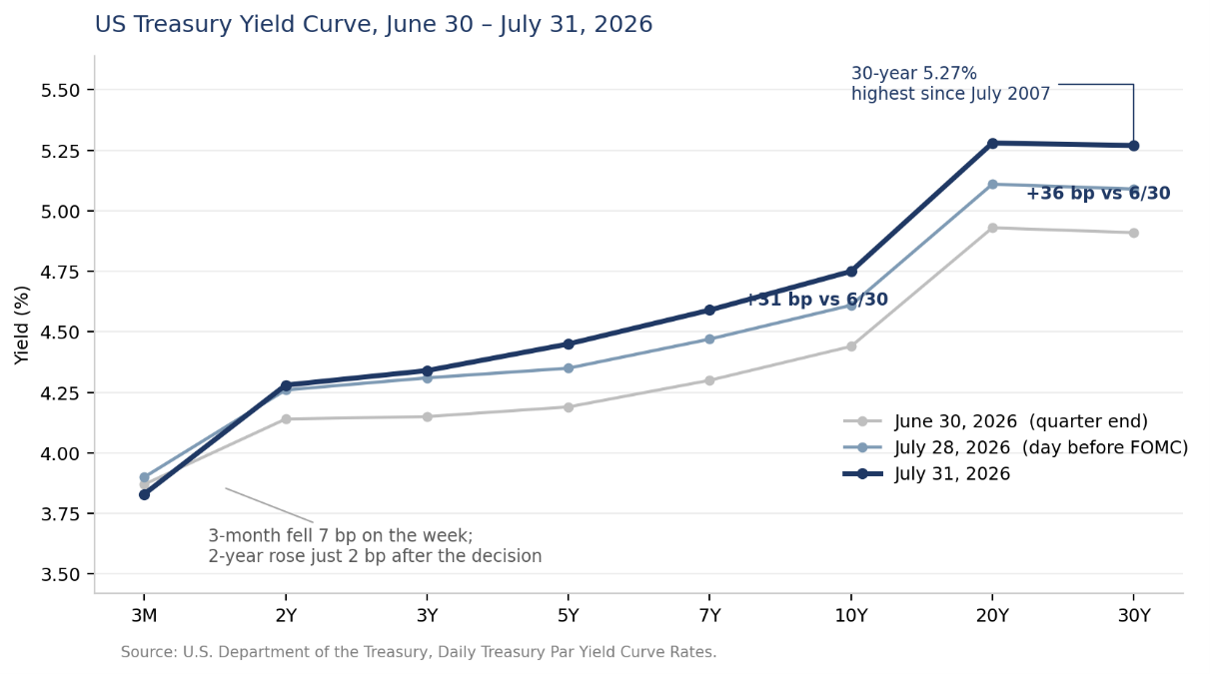
The steepening curve reflects growing concern about longer-term inflation. A near-term rate increase is already priced into short-term rates, with the two-year sitting roughly 65 basis points above the current funds rate. Short-term rates moved little when July’s increase did not come. The additional yield investors demanded came almost entirely at the long end, where buyers of 10- and 30-year Treasuries require compensation for inflation eroding principal over the life of the bond. For commercial real estate investors, this means that the modest relief previously anticipated from rate cuts this year has been withdrawn.
The Alpha Investing Strategy
Against a backdrop of inflation above target, a Federal Reserve that has moved from expected easing toward a possible increase, and a long end of the Treasury curve at its highest level in nearly two decades, our investment approach remains disciplined and selective, focused on fundamentally sound real estate with outsized upside potential relative to downside risk. We continue to emphasize assets with durable in-place cash flow, conservative capital structures, fixed-rate debt or rate caps, and clear paths to value creation and operational improvement that do not depend on aggressive rent growth or cap rate compression. We are also placing more weight on the duration of the income we buy and on matching the tenor of debt to it, since the curve no longer offers a free choice between short-term and long-term borrowing.
Senior housing continues to stand out as the most attractive risk-adjusted opportunity in commercial real estate. Accelerating demographic demand, supply pipelines at multi-decade lows, and a fragmented operator base create conditions in which experienced operators can acquire assets at attractive bases and drive meaningful value through improved management, staffing, and operating efficiency. We can still selectively find transactions with going-in cap rates in the high single digits to low double digits, materially above those of competing asset classes. We believe these opportunities will continue to exist even if rates move higher. The sector is also well positioned to weather a steepening curve, because senior housing income reprices continuously. Resident agreements generally renew annually or monthly, so cash flows adjust to inflation in a way that a fixed-escalator lease cannot.
Our position on multifamily is a matter of timing, not fundamentals. Demand is strong, the supply pipeline is contracting, and the pool of deferred renter households is large and growing. We expect those conditions to favor owners over the medium and long term. However, we are not buying at current pricing. Sellers are underwriting those conditions into today’s price, leaving the buyer to assume all of the execution risk and retain none of the margin. Our focus is on protecting our existing portfolio and selectively evaluating structured capital opportunities arising from the refinancing cycle, where pricing reflects the risk assumed.
We continue to evaluate select single-tenant net lease (STNL) transactions, which offer long-term, credit-anchored income with limited operating risk, but we are more cautious on the sector than we have been in prior quarters. A net lease with ten to twenty years of remaining term and fixed escalators is functionally a corporate bond secured by real estate. With the 30-year at its highest level since 2007, the going-in yield required to make such an asset attractive has risen.
Across our existing portfolio, proactive asset management remains a priority, with continued focus on optimizing operations, controlling expenses, strengthening tenant retention, and preserving liquidity. A subset of our portfolio retains floating-rate debt with near-term maturities, and the value of holding power increases in an environment where relief from lower rates is no longer expected. We continue to secure that holding power through loan modifications, additional capital, and operational improvements.
Looking ahead through the rest of 2026, we expect conditions to remain uneven. The Federal Reserve’s posture has hardened, energy prices have turned higher again, and the rate structure that determines commercial real estate values is unlikely to become materially more accommodating in the near term. At the same time, supply is contracting across the sectors we favor, and pricing has stopped falling. Our strategy is to remain patient, deploy capital selectively where risk-adjusted returns are compelling, and position the portfolio to benefit as the market moves toward a more balanced phase of the cycle.
Economic and market data as of July 31, 2026. Petroleum figures reflect July 31 spot prices; retail gasoline reflects the July 27 weekly survey.